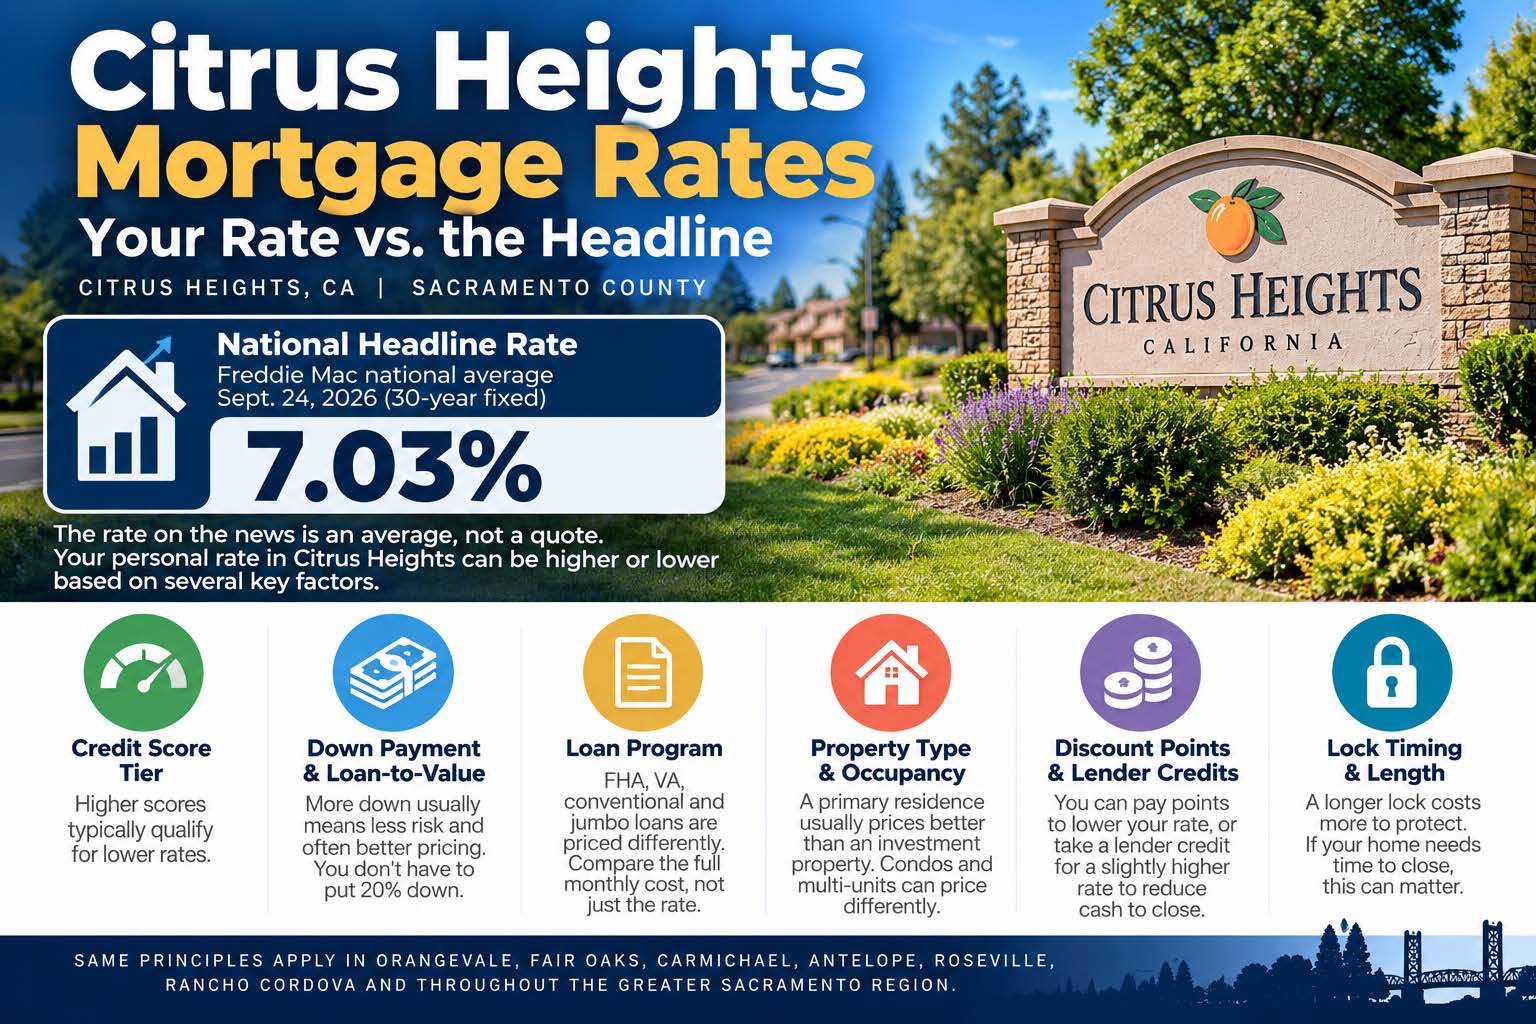
If you are searching "Citrus Heights mortgage rates" late at night, you probably saw a big number on the news and felt your stomach drop. Freddie Mac's weekly survey put the average 30-year fixed rate at 7.03% for the week of September 24, 2026, up from 6.30% a year earlier. That is a real change, and it is fair to feel it.
Here is the part the headlines leave out: that number is an average across the country, built from borrowers with a wide mix of credit, down payments, and loan types. It is not a quote, and it is not a prediction of what you will be offered. Two Citrus Heights buyers can apply on the same day and see meaningfully different rates, and neither one is being treated unfairly. Their profiles are simply different.
Let's walk through what actually builds your rate, so you can spend your energy on the parts you can influence. (For why rates climbed this month, see what the September Fed decision means for buyers.)
What does the weekly rate survey really tell you?
Short answer: direction, not your price. Freddie Mac's survey is a useful thermometer for which way the market is moving. It does not tell you what you will pay, because lenders price each loan based on risk and structure. Think of it like a national average car insurance premium: helpful context, not a personal quote.
Rates also change daily, sometimes more than once a day, while the weekly survey is a snapshot. That is why a quote only means something when it is tied to a date, a loan program, and a lock period.
What six things move your mortgage rate?
- Credit score tier. Pricing typically moves in tiers, so a small score improvement can matter more if it pushes you across a tier line. A mortgage advisor can show you where those lines sit before you apply, and a quick review may reveal a simple fix, such as paying a card balance down before the statement date.
- Down payment and loan-to-value. More down usually means less lender risk and often better pricing. That does not mean you must put 20% down. Many Sacramento County buyers use FHA, conventional low-down-payment options, or down payment assistance to get in with far less.
- Loan program. FHA, VA, conventional, and jumbo loans are priced differently. FHA and VA rates can be competitive, but FHA carries mortgage insurance and VA has a funding fee unless you are exempt. The right comparison is the full monthly cost, not the rate alone.
- Property type and occupancy. A primary residence usually prices better than an investment property. A condo or a two-to-four-unit property can price differently than a single-family home.
- Discount points and lender credits. You can sometimes pay points up front to lower the rate, or take a lender credit for a slightly higher rate to reduce cash to close. Neither is "better." It depends on how long you plan to keep the loan.
- Lock timing and length. A longer lock costs more to protect. If the home you are buying needs extra time to close, that matters.
How much does the rate change a monthly payment?
Hypothetical example, not a quote: a $400,000 loan on a 30-year fixed term. Principal and interest only (no taxes, insurance, HOA, or mortgage insurance). The rates below are used only to show the math; they are not offers and are not APRs.
- At 7.03% (the Freddie Mac average for the week of September 24, 2026): about $2,669 a month.
- At 6.30% (the average one year earlier): about $2,476 a month, roughly $193 less.
- At 6.78% (an illustrative rate for a profile that prices better than average): about $2,602 a month, roughly $67 less than at 7.03%.
Your numbers will differ. The point is that the pieces of your own profile, and the way the loan is structured, can move your payment in a way the national headline never shows. That is why a conversation about your specific scenario is worth more than watching the news.
What is happening in the Citrus Heights housing market?
According to Redfin, the median sale price in Citrus Heights was about $484,679 in August 2026, up about 0.3% from a year earlier, and homes typically went under contract in about 22 days. (Redfin is a data aggregator; local MLS figures can differ.)
For buyers, roughly flat prices alongside higher rates is a combination worth understanding. Prices have not surged, which keeps the loan amount in a more manageable range for many first-time buyers than in higher-priced parts of California. The trade-off is the higher monthly cost from the rate, which is why structure matters so much right now. If you are looking nearby, the same principles apply in Orangevale, Fair Oaks, Carmichael, Antelope, Roseville, and Rancho Cordova.
Can buying still build wealth when rates are higher?
The Federal Reserve's 2022 Survey of Consumer Finances found that the median net worth of homeowners was about $396,200, compared with about $10,400 for renters and other non-homeowners. That gap reflects many factors, but equity building over time is a big piece. Many buyers choose to buy when the payment fits their budget and life plans, and revisit a refinance if rates ease later. No one can promise rates will fall, so the goal is a payment you are comfortable with today. (More on that decision: buy now vs. wait.)
How do you compare mortgage rate quotes fairly?
Put quotes side by side using the Loan Estimate, the standardized three-page form lenders must provide after you apply. Compare:
- The interest rate and the APR (the APR folds in certain loan costs)
- Points you pay or lender credits you receive
- The estimated monthly payment, including mortgage insurance
- Total cash to close
- The lock period and its expiration date
A quote that looks lower on the rate can cost more once points and fees are counted.
Ken's Take
The buyers who do best in a 7% headline week are not the ones who time the market. They are the ones who know their own numbers: where their credit tier sits, what a point costs versus what it saves, and what payment they can live with. Get those three answers first, then shop.
What should a Citrus Heights buyer do next?
- Pull your credit and know your score range before you shop.
- Decide the monthly payment you are comfortable with, not just the maximum you can qualify for.
- Ask about first-time buyer programs and low-down-payment options that fit Sacramento County.
- Get a written Loan Estimate and compare the total picture.
- Talk with a licensed advisor before you fall in love with a house, so your offer is backed by a real pre-approval.
If you are weighing buying, refinancing, or using down payment assistance, connect with Ken Clark Jr. and the #ChampionsofLoans team at PRMG Mortgage, your Citrus Heights mortgage lender. The right strategy starts with a conversation, not a guess.