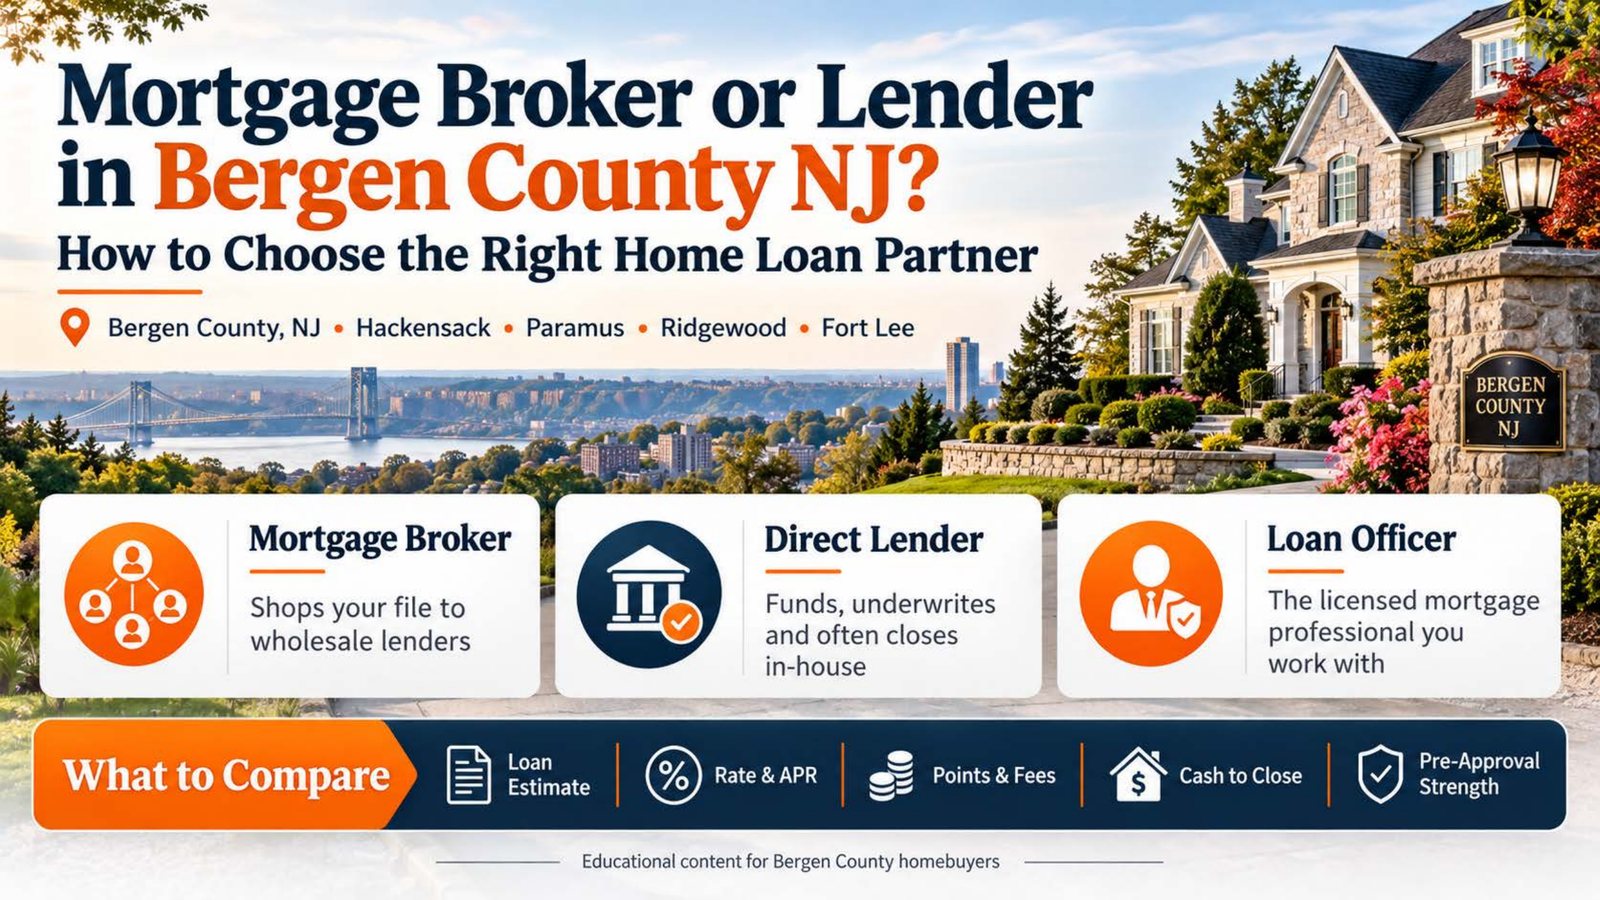
If you are searching "find a mortgage broker in Bergen County NJ," you are already doing the smart thing: you are not just taking the first offer. The financing conversation shapes your monthly payment, your cash to close, and how calm the closing process feels. So let's clear up the confusing part first, because three words (broker, lender, loan officer) get tossed around as if they mean the same thing. They do not.
What is the difference between a mortgage broker, a direct lender, and a loan officer?
A mortgage broker is a licensed company or individual that does not lend its own money. A broker collects your application and submits it to one or more wholesale lenders it works with. The broker's value is choice: it may be able to shop your file across several lenders.
A direct lender makes the loan itself and manages underwriting and closing within its own company. PRMG Mortgage (Paramount Residential Mortgage Group) is a direct mortgage lender. The value is control and communication: for most loans, the team preparing your file works within the same company that makes the decision.
A loan officer is the licensed person you actually talk to. Loan officers can work for a broker or for a direct lender, and they must be licensed or registered through the NMLS. So the useful question is not just "broker or lender." It is "who is my loan officer, how do they communicate, and which programs can they actually deliver?"
Is a broker or a direct lender better?
Short answer: neither is automatically better. Shopping several wholesale lenders sometimes helps. Sometimes a direct lender has a program a broker's lender panel does not. What matters is the total picture: rate, fees, program fit, speed, and how likely the loan is to close smoothly on the date in your contract.
In Bergen County, where sellers often work on tight timelines, reliability can matter as much as a slightly lower rate. A pre-approval that falls apart in underwriting can cost you the house.
What is the Bergen County market asking of buyers right now?
According to Greater Bergen Realtors' June 2026 report, the median sale price for a single-family home in Bergen County was about $921,000, up 6.7% from a year earlier, with 538 closed sales, up 10.7%. The same report put the townhouse and condo median at about $541,225. Prices are still rising while inventory remains limited. (For more on local prices, see Bergen County home prices in 2026.)
Freddie Mac's weekly survey put the 30-year fixed average at 7.03% for the week of September 24, 2026, up from 6.30% a year earlier. That is a national average, not a quote. Put the two together and you can see why the structure of your loan matters so much here. (More on this month's rate move: the September Fed decision and what buyers do now.)
Many Bergen County single-family purchases come close to or above the conforming limit. For 2026, Bergen County's one-unit conforming loan limit is $1,209,750 (set by the FHFA), and its FHA one-unit limit is $1,249,125 (set by HUD). A loan above the conforming limit moves into jumbo financing, which has its own credit, reserve, and down payment guidelines. We break that down in what a jumbo mortgage is in New Jersey.
What should you ask any broker or lender before you choose?
- Who will be my point of contact, and how quickly do you respond? Speed and clarity in the first week often predict the whole experience.
- Which programs fit my situation? Conventional, FHA, VA, jumbo, and for self-employed buyers, non-QM options such as bank statement loans.
- Can you give me a written Loan Estimate? It is the standardized federal form that lets you compare offers side by side.
- Is your pre-approval reviewed by an underwriter, or based on a quick review? An underwriter-reviewed approval generally carries more weight with sellers.
- Who does the underwriting and closing, and what is your typical time to close?
- What fees are involved, and are any lender-paid? Ask about origination fees, points, and lender credits.
- What happens if rates move before I lock? Understand the lock period and the cost of extending it.
How do you compare mortgage offers without getting fooled?
Two quotes with different rates are not truly comparable until you line up the whole page. Look at the interest rate and the APR together, the points or credits, the estimated monthly payment including mortgage insurance, and the cash to close. A lower rate paired with heavy points may cost more if you do not keep the loan long. A slightly higher rate with a lender credit may reduce your cash to close, which can matter on a tight budget. The CFPB's Loan Estimate guide walks through each section.
Why does the choice matter for building wealth?
The Federal Reserve's 2022 Survey of Consumer Finances found that the median net worth of homeowners was about $396,200, versus about $10,400 for renters and other non-homeowners. Many factors contribute, but building equity over time is a large one, and the right financing partner is part of that foundation. First-time buyers may also qualify for New Jersey down payment assistance through NJHMFA and other sources, subject to eligibility and funding. See the New Jersey first-time homebuyer guide.
Ken's Take
In a market like Bergen County, the lowest advertised rate is not the win. The win is a clean approval that closes on the day in your contract, with no surprises in the last week. Ask every option the same seven questions, get a written Loan Estimate from each, and pick the one you trust to deliver.
What does working with PRMG look like?
Ken Clark Jr. is a Certified Mortgage Advisor and Branch Manager at PRMG Mortgage (NMLS #225375). PRMG is licensed in 49 states, excluding New York, including New Jersey. The approach is simple: start with a conversation about your goals, review your options across programs, and give you a plan you can act on, whether you are a first-time buyer in Hackensack, a move-up buyer in Ridgewood, or an investor looking at a two-family. Not every borrower fits every program, which is exactly why the conversation comes first. Learn more about working with a Bergen County mortgage lender, or see New Jersey jumbo loans and Hoboken jumbo financing.